News
NGX September 2026 review: ASI up 2.87 per cent as profit-taking trims the peak
The NGX ASI gained 2.87 per cent in September to 251,211.67 as market cap added N5.37 trillion, before October opened lower on bank profit-taking. The full month in numbers.
Part 2 of 2
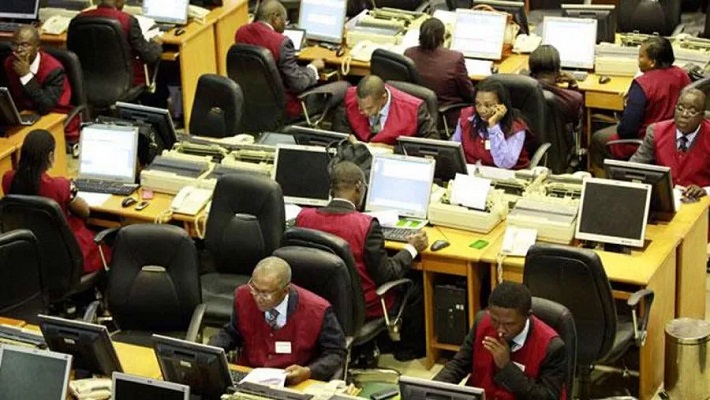
Nigerian equities closed September 2026 firmly in positive territory, with the benchmark NGX All-Share Index rising 2.87 per cent over the month to 251,211.67 points from 244,199.39 at the end of August, adding 7,012.28 points, according to Nairametrics on October 2. Market capitalisation expanded by N5.37 trillion, or 3.40 per cent, to approximately N163.10 trillion from N157.74 trillion. Daba Finance confirmed the same month tally and noted the market touched a historical N164 trillion mark intra month.
BusinessDay summed up the stock picking backdrop: selected names posted double digit gains as participants repositioned across real estate, transport, energy, financial services and market infrastructure.
How the month was built
First week. The ASI gained 2.36 per cent to 246,992.44 and market capitalisation rose 2.40 per cent to N159.559 trillion, lifting the year to date return to 58.72 per cent, according to BusinessDay. The Oil and Gas Index led with a 9.10 per cent weekly gain, followed by Commodity at 5.99, Insurance at 3.85, Premium at 3.73 and Banking at 3.58 per cent. Turnover hit 4.360 billion shares worth N210.331 billion across 223,284 deals, with breadth at 56 gainers against 35 decliners.
Record peak. On September 28 the market printed the N164 trillion record: ASI 252,635.11, up 0.21 per cent, on 1.024 billion shares. Liquidity for the rally drew on the same forces behind the September 29 OMO session: reserves at an 18 year high, Frontier Market return, and heavy two way CBN flows.
Month end drag. On September 30 the ASI contracted by 701.53 points to 251,211.67 from 251,913.20, down 0.28 per cent, and capitalisation shed N425.73 billion to N163.10 trillion from N163.53 trillion, according to Nairametrics. Volume stayed high at 1.035 billion shares, up 87.73 per cent from 548.65 million, across 44,398 deals. The Banking Index fell to 2,712.10 from 2,727.81 and Insurance to 1,087.10 from 1,098.22, while Industrial Goods advanced to 10,440.27, Growth to 27,452.85, Consumer Goods edged to 4,058.25, Oil and Gas ticked to 6,246.86 and the Main-Board rose to 10,870.19. The Premium Index retreated to 31,771.57 from 32,100.41.
VFD Group dominated the September 30 tape with 367.32 million shares worth N4.86 billion, about 35.5 per cent of market volume, according to InvestorsKing, followed by UAC of Nigeria at 158.18 million shares, though UAC led on value at N21.51 billion. The five most active names took about 67.7 per cent of volume.
October opens lower
Thursday, October 1 was a market holiday for Independence Day, with no trading. On Friday, October 2 the ASI slipped by 403.40 points, or 0.16 per cent, to 250,808.27 from 251,211.67, and capitalisation contracted by N261.92 billion to N162.84 trillion, according to Nairametrics. Volume cooled to 557.13 million shares, down 45.91 per cent, while deals rose 20.21 per cent to 53,370.
The drag came from familiar names: FirstHoldco down 6.16 per cent, NGX Group down 6.85 per cent and VFD Group down 6.90 per cent, pulling the Banking Index down 0.97 per cent to 2,685.71. That overshadowed gains in Fidelity Bank at plus 8.55 per cent and GTCO at plus 0.61 per cent. Insurance outperformed, up 1.21 per cent to 1,100.30, led by AIICO at plus 10.00 per cent to N4.18 with AXA Mansard plus 3.64 per cent and Consolidated Hallmark plus 4.49 per cent. Breadth was exactly neutral at 26 gainers to 26 losers. Access Holdings led volume at 183.56 million shares. PZ Cussons paced losers at minus 9.91 per cent to N66.40.
What September means for Q4
Three threads carry into the final quarter. First, the cost of money channel: the MPR reset to 23 per cent plus September OMO allotments near N12.8 trillion set a lower anchor with tight liquidity, a mix our OMO auction note unpacks. Second, the flow channel: record capitalisation with month end profit-taking is healthy rotation only if breadth and turnover persist into Q3 earnings season. Third, valuations: Nairametrics flagged overbought signals in late September and stretched valuations as a Q4 risk, so earnings, not momentum, decide whether the N163 trillion zone holds.
What to watch
- Q3 earnings and filings: starting with banks, where Access’s extended H1 timeline and Q3 prints set the tone.
- Dangote refinery IPO window: the offer runs September 14 to October 13, a live demand gauge for primary market appetite alongside secondary rotation.
- Liquidity operations: whether October OMO stays above maturities or lets the N8.57 trillion peak liquidity sit.
- Breadth: advancers holding near or above decliners on up days, rather than cap-only gains.
Frequently asked questions
Frequently asked questions
How did the NGX perform in September 2026?
The ASI rose 2.87 per cent to 251,211.67 from 244,199.39, adding 7,012.28 points, while market capitalisation grew N5.37 trillion, or 3.40 per cent, to about N163.10 trillion, per Nairametrics. The market touched N164 trillion intra month.
Why did the market fall on September 30 and October 2?
Banking and financial names faced profit-taking after a strong month. September 30 shed N425.73 billion with Banking and Insurance lower, and October 2 shed N261.92 billion with FirstHoldco, NGX Group and VFD Group down between 6 and 7 per cent, per Nairametrics.
Was October 1 a trading day?
No. The NGX was closed on October 1 for Nigeria’s Independence Day, so the week ran Monday to Wednesday plus Friday.
Verify: cross-check month totals and daily closes on the NGX website.