Tutorials
3 secrets to going from income earning to wealth
We are past the halfway mark of 2026. If your income is still your only source of money, this post is for you. Join our free masterclass this Friday 6pm to.
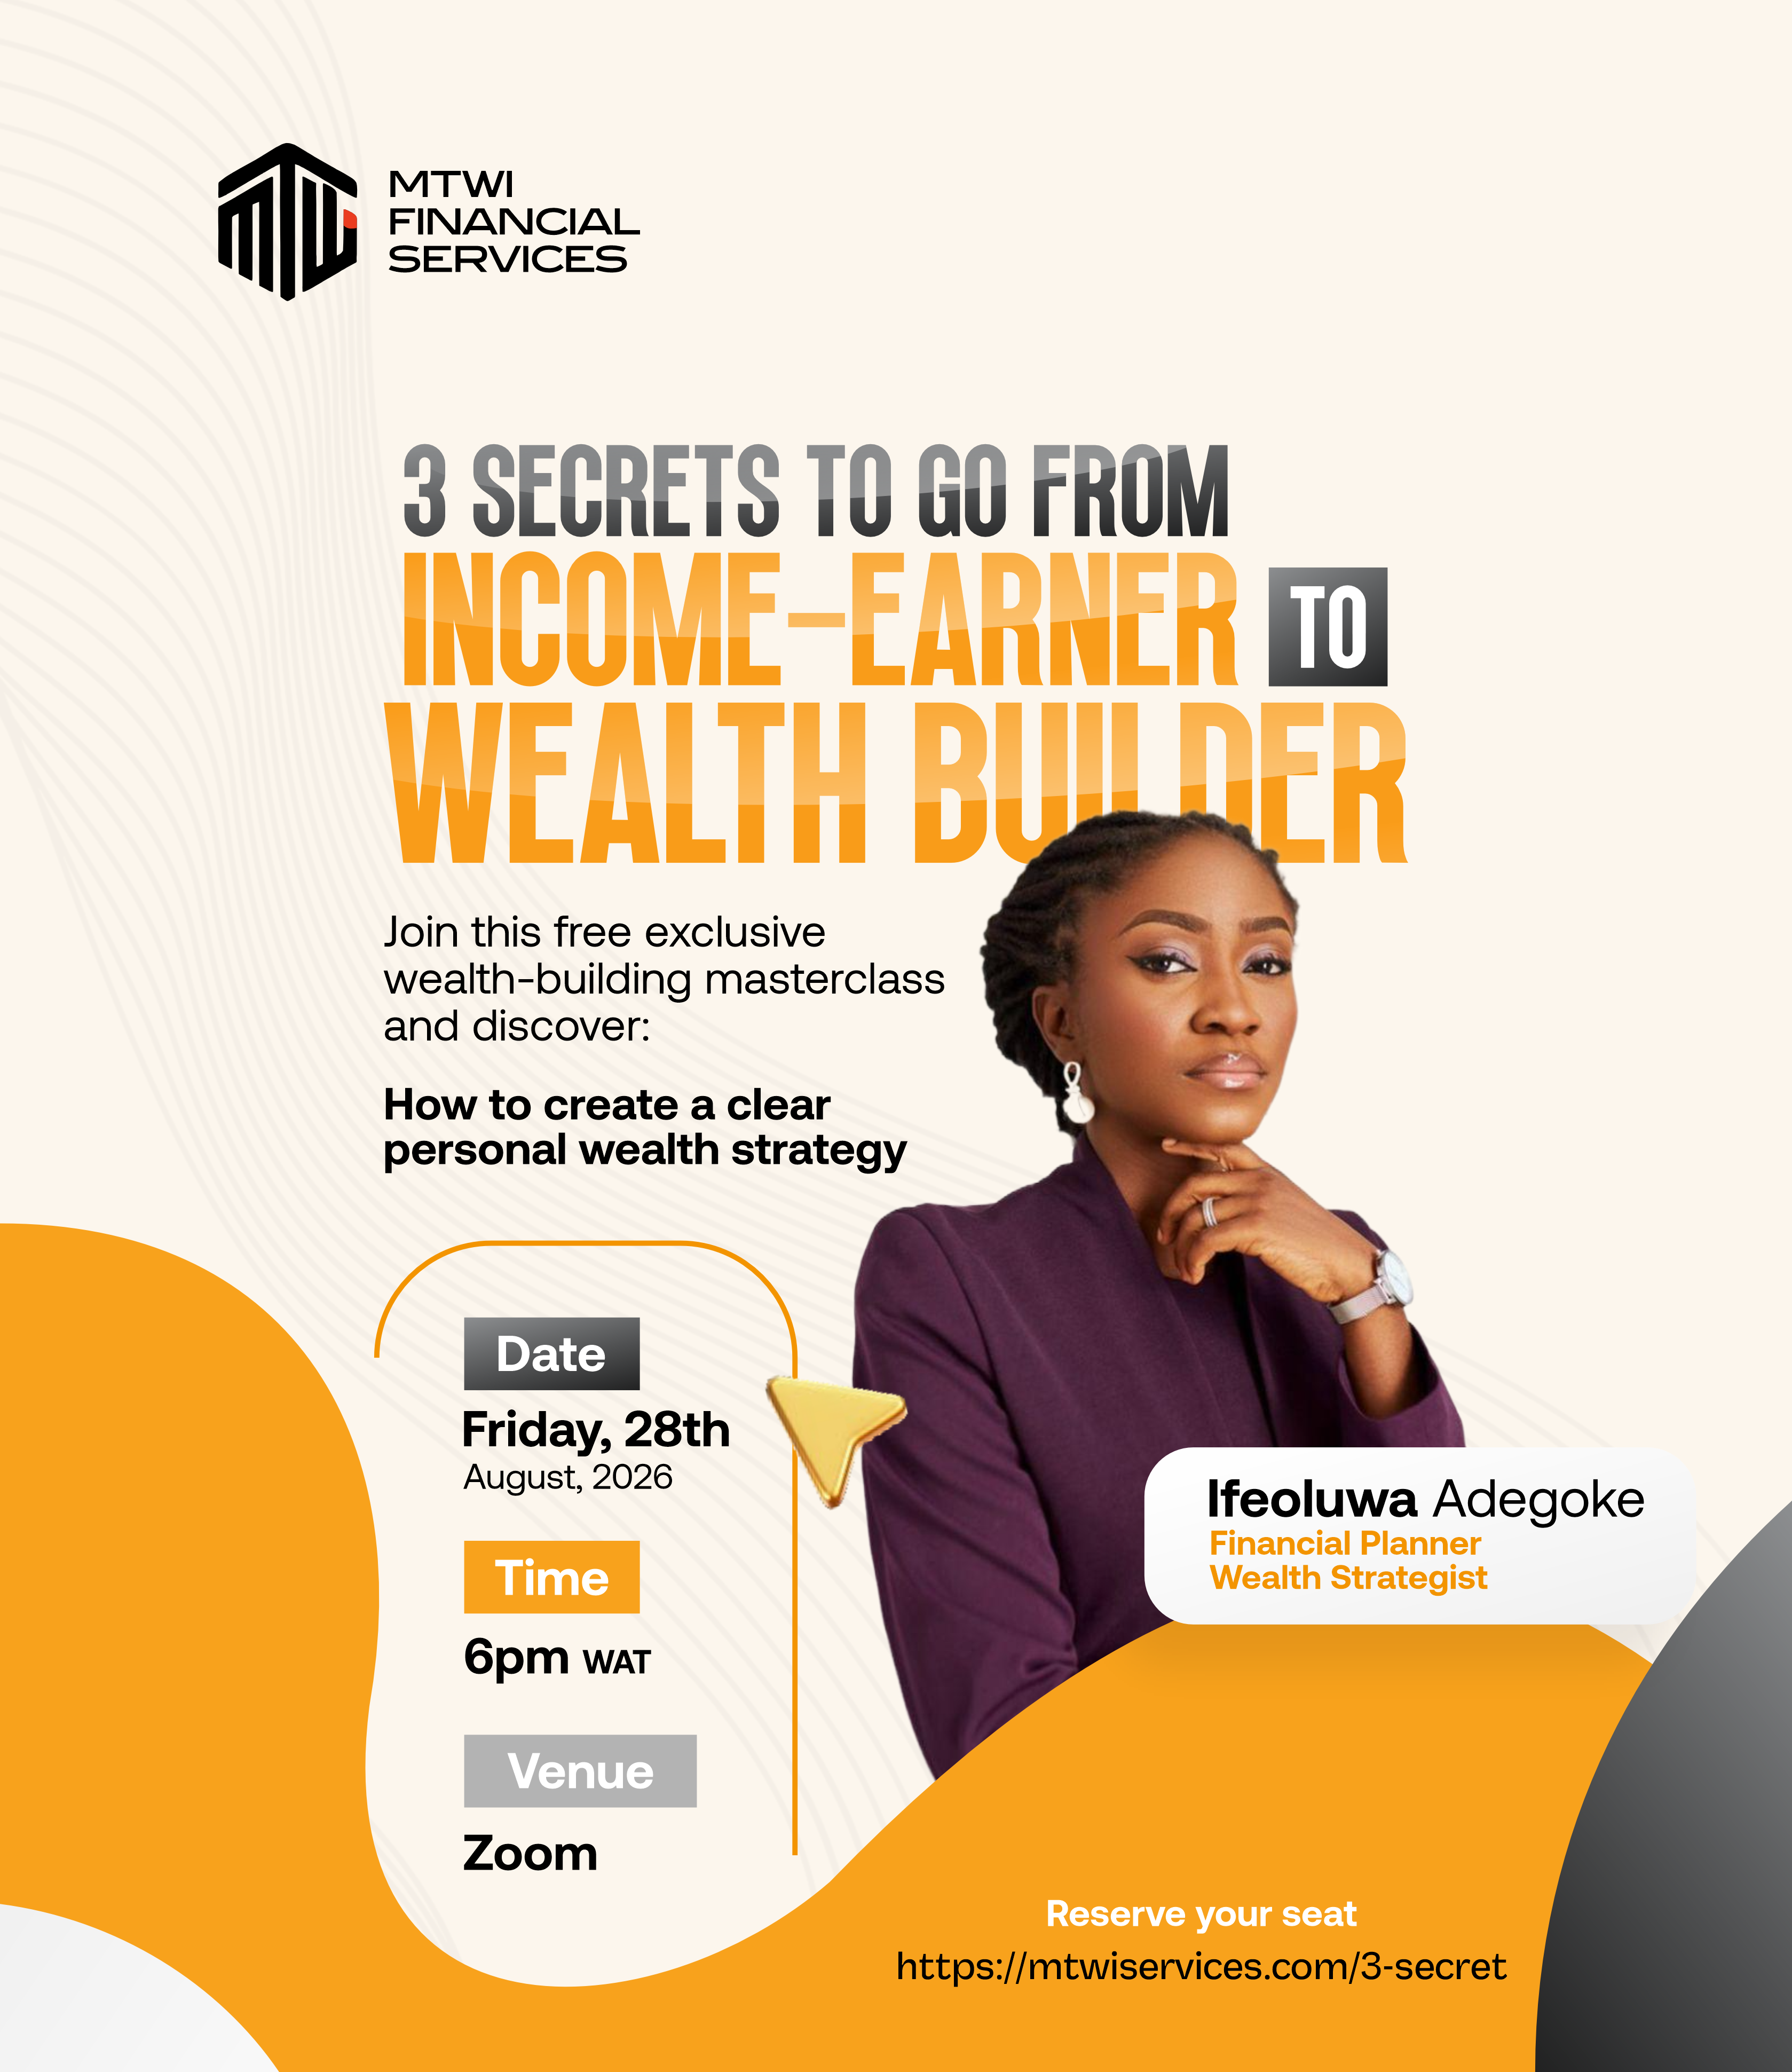
So here we are. Past the halfway mark of 2026.
Take a second and ask yourself something honest. Has your money made you more money this year? Not your salary. Your actual money. The stuff sitting in your account after the bills are paid.
If the answer is no, something has to give.
Most of us grow up thinking about money one way. You work, you earn, you spend. That is income earning. And it is fine as far as it goes. But it will never build wealth on its own. Not because you are bad with money, but because the math does not work that way.
Wealth building is a different game. It happens when the money you already have starts doing some of the heavy lifting. When your investments, your assets, your portfolio start putting money back in your pocket while you sleep.
The difference is not about how much you earn. It is about what you do with what you keep.
The first thing nobody tells you
The biggest thing holding people back is not a small salary or a bad economy. It is the stories they carry around in their head about money. That investing is for rich people. That the market is gambling. That you need to know everything before you start.
These beliefs sit underneath every financial decision you make, quietly nudging you toward safe choices that keep you stuck exactly where you are. The first real shift is not about picking the right stock. It is about recognising that your mindset is the thing that has to move first.
Then there is the spending thing
There is a real difference between spending money and putting it to work. Most people never make that distinction.
Spending consumes value. Putting money to work grows it. The people who build wealth look at every naira differently. Not as something to spend, but as something to deploy. Into assets that pay dividends. Into things that appreciate. Into vehicles that generate returns.
This does not mean living like a monk. It just means asking one question before money leaves your account: is this covering a real need, or is this going to work for me?
And the part everyone skips
Here is the one most people miss. They get inspired, they read a book, they feel motivated. And then they try to brute force their way to wealth using pure discipline. It never lasts.
The people who actually build wealth do not rely on willpower. They build systems. Standing orders. Automated investments. Scheduled reviews. Things that keep running whether you feel motivated or not. Consistency beats intensity every single time.
Half the year is already behind us. Another year of inflation eating into your savings while cash sits idle is not the move.
You do not need a massive salary to start. The first shift is mental, not mathematical. The second is about how you direct what you already have. And the third makes sure you actually follow through without having to think about it every day.
Spots are limited. Grab your spot now.
Common mistakes and how to avoid them
- Treating the app as the market. Your broker or fintech shows a price, but settlement, ownership, and corporate actions sit with CSCS. If you skip the CSCS step you own the display, not the asset. Use our CSCS guide to confirm the account that actually holds the securities.
- Mixing up yield and return. A T-bill yield, a money market rate, and a stock dividend yield are quoted differently and land at different times. Map each to when cash actually hits your account using the Treasury bills starter and the FGN Savings Bonds walkthrough.
- Forgetting the settlement clock. Since June, NGX trades settle on T plus 1. If you sell to fund a new purchase, the cash is not instant. Check settlement timing in our T plus 1 explainer before you chain trades.
Keep a single checklist for every new product: where the asset is held, when cash settles, what fees apply, and where you verify the quote. Run that four-point check and most of the avoidable errors disappear.
Frequently asked questions
Where can I verify the numbers you quote?
Check the NGX disclosure or the CBN data page for the date we cite. Every figure in this note is tied to its source so you can confirm it independently.
Do I need to act immediately on this update?
No. Use the levels as reference points and confirm the latest price, settlement date, and corporate action timeline with your broker or CSCS before you act. Our how to apply for an IPO guide walks through the verification steps.
Common mistakes and how to avoid them
- Treating the app as the market. Your broker or fintech shows a price, but settlement, ownership, and corporate actions sit with CSCS. If you skip the CSCS step you own the display, not the asset. Use our CSCS guide to confirm the account that actually holds the securities.
- Mixing up yield and return. A T-bill yield, a money market rate, and a stock dividend yield are quoted differently and land at different times. Map each to when cash actually hits your account using the Treasury bills starter and the FGN Savings Bonds walkthrough.
- Forgetting the settlement clock. Since June, NGX trades settle on T plus 1. If you sell to fund a new purchase, the cash is not instant. Check settlement timing in our T plus 1 explainer before you chain trades.
Keep a single checklist for every new product: where the asset is held, when cash settles, what fees apply, and where you verify the quote. Run that four-point check and most of the avoidable errors disappear.
Where can I verify the numbers you quote?
Check the NGX corporate disclosure, the CBN auction result page, or the company filing. We cite each figure with its source and date so you can cross-check before you act.